Fixed price
You agree on a scope and a number. The contractor delivers that scope for that price regardless of what it actually costs them.
**What's good:**
- You know your number, and you can plan around it
- The contractor absorbs the risk of underestimating labor or material
- Efficiency benefits them, which means they have every reason to move quickly
**What's not:**
- **You pay a risk premium.** A contractor pricing a fixed job on an old house has to price for the bad outcome, not the likely one. That premium is real, typically 5–15%, and you pay it whether or not the risk materializes.
- **Change orders become adversarial.** Every deviation is a negotiation, because the contractor's margin depends on the scope not growing.
- **You never see the real numbers.** If the job comes in well under, that's the contractor's upside.
- **It requires a fully defined scope.** Every selection made, every unknown resolved. On a gut renovation of a 1920s house, that's not possible.
**Best for:** kitchens and bathrooms with all selections made, additions with complete drawings, defined scopes in newer houses.
Cost-plus
You pay the actual cost of labor, materials and subcontractors, plus a fee — either a percentage or a fixed dollar amount.
**What's good:**
- **No risk premium.** You pay what it costs. On a job where the unknowns don't materialize, you keep the savings.
- **Full transparency.** You see invoices, labor hours, subcontractor bills.
- **Change orders stop being fights.** A scope change is just a different cost, not a renegotiation.
- **It works when the scope can't be known** — restoration rebuilds, gut renovations, anything where opening the walls determines the work.
**What's not:**
- **No cap.** Your exposure is genuinely open-ended.
- **The incentive can run the wrong way** with a percentage fee — a higher cost produces a higher fee. A **fixed-dollar fee** removes that problem entirely and is worth insisting on.
- **It requires trust and administration.** You need a contractor who documents thoroughly and you need to actually read what they send.
**Best for:** restoration and insurance rebuilds, gut renovations of old houses, projects where discovery determines the scope.
Cost-plus with a guaranteed maximum price
You pay actual costs plus a fee, but the total cannot exceed an agreed ceiling. Above the cap, the contractor absorbs it.
**Why this is usually the best structure on a large remodel:**
- You get cost-plus transparency
- You get fixed-price certainty on your worst case
- The risk premium is smaller than a straight fixed price, because the contractor's exposure is only above the cap
- Savings below the cap can be shared or returned to you — negotiate this explicitly
**What to negotiate:**
- **Who keeps savings below the GMP?** Common arrangements: all to the owner, or a split. Decide before signing.
- **What can raise the cap?** Owner-directed scope changes and genuinely concealed conditions, usually. Contractor estimating errors, no.
- **A fixed-dollar fee,** not a percentage, so the fee doesn't grow with the cost.
Protections that matter in any structure
**Regardless of which you choose:**
1. **A written scope of work.** Detailed, by area and trade. This is what everything else references.
2. **A written change order process.** Priced and signed by you *before* the work proceeds.
3. **A payment schedule tied to completed milestones,** not to the calendar.
4. **Lien releases** from subcontractors and suppliers with each payment. In Washington, unpaid subcontractors can lien your property even if you paid the general contractor. Conditional lien waivers with each draw are the protection.
5. **A named contingency** for discovered conditions, so a surprise doesn't become a fight.
6. **Written warranty terms.**
7. **Verified registration, bond and insurance** — check at L&I's Verify a Contractor tool before signing.
The Washington-specific pieces
**Registration and bond.** All contractors working in Washington must be registered with the Department of Labor and Industries. As of July 1, 2024, general contractors carry a **$30,000 bond** and specialty contractors **$15,000** — the first increase since 2001. That bond is the fund a homeowner can make a claim against if things go badly.
**Lien rights.** Washington's construction lien statute lets subcontractors and material suppliers place a lien on your property for unpaid work, even if you have paid the general contractor in full. Lien releases with each payment are not paperwork — they're the mechanism that protects you.
**Notice to Customer.** Washington requires contractors to provide a disclosure statement to residential customers on certain contracts. If you didn't receive one, ask why.
How to choose
**Fixed price if:** the scope is fully defined, every selection is made, the house is newer or the work is contained, and certainty is worth a premium to you.
**Cost-plus with a fixed fee if:** the scope genuinely can't be known — restoration, a gut, structural work in an old house — and you're willing to read documentation and stay engaged.
**Cost-plus with a GMP if:** it's a large project with some unknowns, and you want transparency plus a ceiling. For most whole-home remodels this is the right answer.
**Never:** a handshake, a one-page number with no scope, or a percentage-fee cost-plus with no cap and no documentation requirement.
How Fortress Build & Finish contracts
We write fixed price on defined scopes — a kitchen with selections made, a bathroom, an addition with complete drawings — because that's what fixed price is for, and we'd rather carry that risk than have you carry an unpriced one.
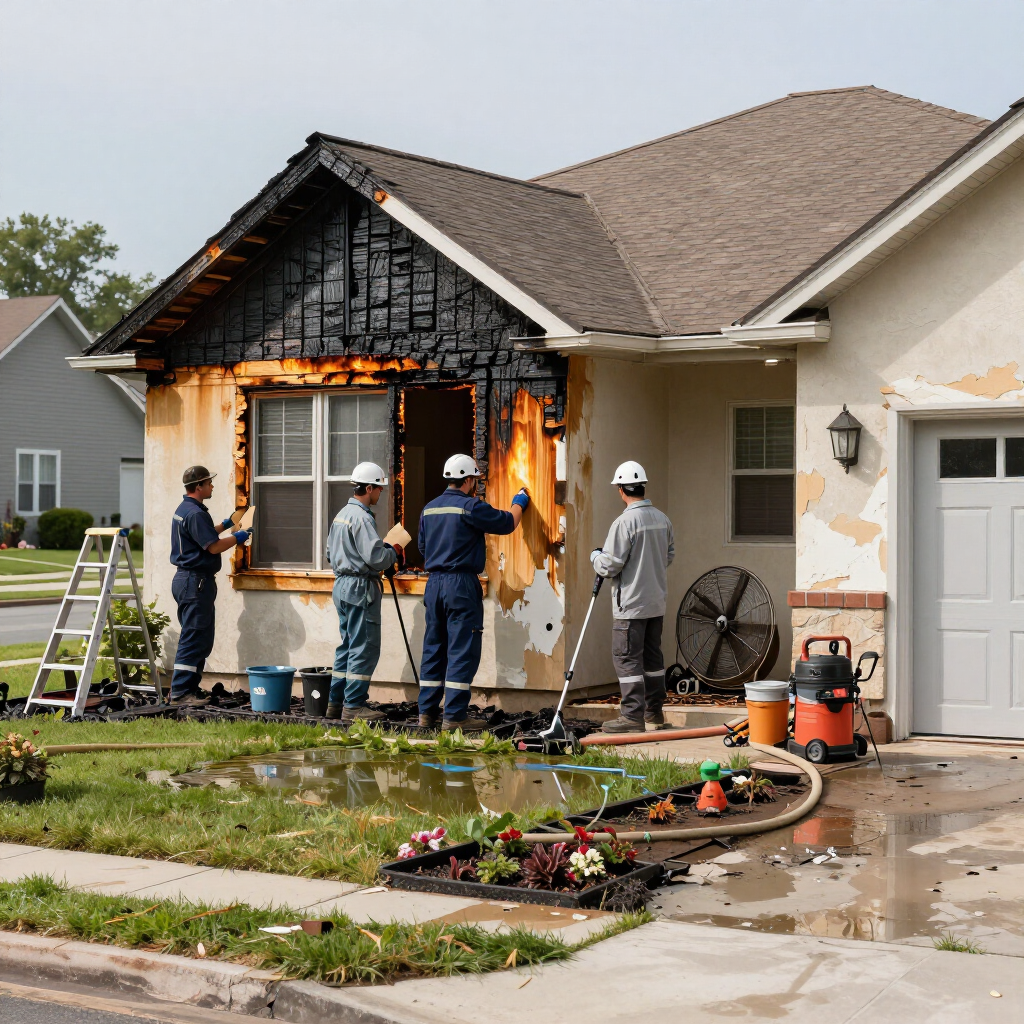
On restoration rebuilds and gut renovations, where the scope is genuinely determined by what's behind the wall, we work cost-plus with documentation, or cost-plus with a GMP where you want a ceiling. Either way the numbers are itemized and the change order process is written before work starts.
Frequently asked questions
Is fixed price or cost-plus better for a homeowner?
Fixed price is better when the scope is fully defined and certainty matters. Cost-plus is better when the scope genuinely can't be known in advance, like a restoration rebuild. Cost-plus with a guaranteed maximum price combines much of both.
What is a fair cost-plus fee?
Commonly 10–20% of cost. A **fixed-dollar fee** is better than a percentage, because a percentage fee grows when costs grow.
Does fixed price mean the price can't change?
No. It fixes the price for the agreed scope. Owner-directed changes and genuinely concealed conditions still generate change orders.
What is a guaranteed maximum price?
A cost-plus contract with a ceiling. You pay actual costs plus fee up to the cap; above the cap the contractor absorbs it. Negotiate who keeps savings below the cap.
How do I protect myself from liens in Washington?
Get conditional lien releases from subcontractors and suppliers with each payment. Washington's lien statute allows unpaid subs to lien your property even if you paid the general contractor in full.
---
**About the author.** Ryan Watt is the marketing director at Fortress Build & Finish, a Seattle-owned finish contractor with more than 25 years in residential and commercial remodeling, custom carpentry, tile installation, and fire and water damage restoration.
*Fortress Build & Finish —
(206) 426-2067 · Licensed, bonded and insured — License No. FORTRBF756KA · Serving Seattle, Ballard, Magnolia, Queen Anne, West Seattle, Capitol Hill, Wallingford, Bellevue, Kirkland, Renton, Shoreline, Edmonds and the surrounding communities ·
fortressbuildfinish.com*